ShopeePay Accelerates Digital Financial Inclusion Through Strategic QRIS Adoption for Indonesian SMEs

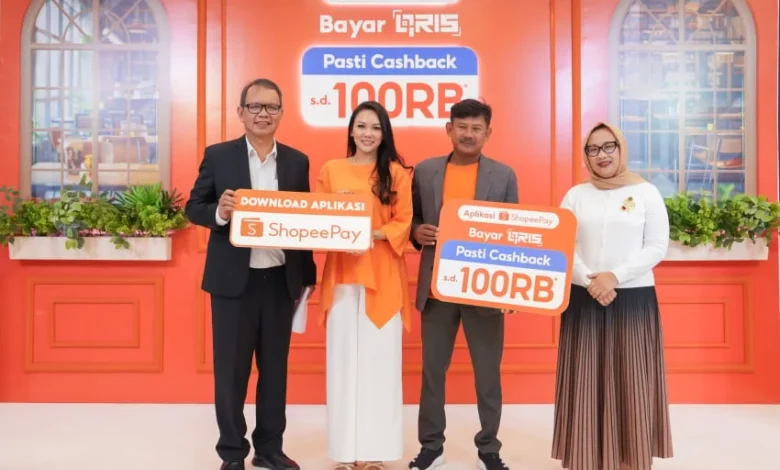
The rapid proliferation of Quick Response Code Indonesian Standard (QRIS) technology has fundamentally transformed the transactional landscape in Indonesia, positioning itself as a cornerstone of the nation’s digital economy. As Bank Indonesia (BI) continues its aggressive push toward a fully integrated digital payment ecosystem, major fintech players such as ShopeePay are playing a pivotal role in bridging the gap between consumers and micro, small, and medium enterprises (MSMEs). This synergy was prominently highlighted during the "Cara Baru Manfaatkan QRIS: Pengguna & Pengusaha UMKM Pasti Untung" event held on September 16 in Jakarta, where stakeholders reaffirmed their commitment to digitizing the informal economy through seamless, secure, and efficient payment solutions.
The Evolution of Digital Payments in Indonesia
To understand the current momentum of QRIS, one must look at the historical trajectory of payment systems in Indonesia. Prior to the standardization introduced by Bank Indonesia on August 17, 2019, the market was fragmented, with various e-wallet providers utilizing proprietary, non-interoperable QR codes. This lack of standardization created significant friction for merchants, who were forced to display multiple QR codes to accommodate different applications, and for consumers, who faced limited accessibility.
The implementation of QRIS served as a watershed moment. By creating a unified standard, Bank Indonesia successfully fostered an environment where any QRIS-enabled application could process transactions at any QRIS-enabled merchant. Over the past five years, the adoption rate has accelerated exponentially. From a handful of pilot programs in late 2019, the ecosystem has matured into a ubiquitous infrastructure present in traditional wet markets, urban shopping centers, and even rural convenience stores.
Strategic Synergy: ShopeePay and the MSME Sector
During the September 16 forum, industry experts and policymakers discussed the symbiotic relationship between digital payment platforms and the grassroots economy. ShopeePay, by integrating its services into the broader Shopee ecosystem, has provided a comprehensive suite of financial tools that extend beyond simple payments.
For the average consumer, the ShopeePay application functions as a "super-app" entry point. By consolidating payment capabilities, voucher distribution, and transaction history, the platform reduces the cognitive load of digital banking. However, the impact is arguably more profound on the supply side—specifically for MSMEs. By lowering the barrier to entry for digital financial services, ShopeePay allows small-scale entrepreneurs to access transaction data, which in turn can serve as a foundation for credit scoring and financial literacy initiatives.
Data-Driven Perspectives on Financial Inclusion
The scale of this transition is supported by compelling statistics provided by regulatory bodies. Fitria Irmi Triswati, Executive Director of the Payment System Policy Department at Bank Indonesia, emphasized the significance of current adoption metrics during the event. According to the latest data, approximately 96.69% of the 45.46 million QRIS merchants in Indonesia are categorized as MSMEs.
This data point is critical for several reasons. First, it demonstrates that the digitalization of the Indonesian economy is not merely a top-down phenomenon driven by large corporations, but a grassroots movement supported by small business owners. Second, it highlights the efficiency gains for micro-entrepreneurs who previously relied exclusively on cash. Cash-based transactions entail hidden costs—including the risk of loss, the time required for manual reconciliation, and the lack of digital proof for business performance. QRIS mitigates these risks, providing a transparent audit trail that is essential for business growth and formalization.
Analyzing the "Cara Baru Manfaatkan QRIS" Event
The event held on September 16 served as a strategic dialogue between regulators, fintech service providers, and business owners. The core objective of the forum was to educate both users and merchants on the long-term benefits of moving away from cash-only operations.

During the discussions, it was noted that while technical adoption is high, the "usage intensity" remains the next frontier. Merely possessing a QRIS sticker is insufficient if the merchant does not actively encourage its use. ShopeePay’s strategy in this regard has been to incentivize both parties through promotional campaigns, loyalty programs, and an intuitive user interface that reduces the time-per-transaction to mere seconds.
Industry analysts observe that such events are essential for addressing the "trust gap." Despite the safety features embedded in the QRIS protocol—including encryption and real-time transaction monitoring—some segments of the population remain wary of digital systems. By bringing together the regulator (Bank Indonesia) and the service provider (ShopeePay), the event provided a platform for public assurance, demonstrating that the digital ecosystem is backed by rigorous security standards and government oversight.
The Broader Economic Implications
The push for QRIS adoption is deeply intertwined with the broader goal of "Indonesia Emas 2045," a national vision to achieve economic maturity and prosperity. A digitized economy is inherently more efficient. It allows for better tax compliance, more accurate economic data collection, and a more robust mechanism for the government to distribute subsidies and financial aid to those who need it most.
Furthermore, the integration of ShopeePay into the daily lives of millions creates a feedback loop. As consumers become more accustomed to digital payments, their demand for digital banking services increases. This creates an opportunity for banks and fintech companies to offer more sophisticated products, such as micro-insurance, small-scale loans, and investment tools, all of which are accessible through the same mobile interfaces that people use to buy their morning coffee or groceries.
Challenges and Future Outlook
Despite the progress, the path forward is not without challenges. Infrastructure reliability, particularly in Indonesia’s remote areas, remains a hurdle. Connectivity issues can occasionally lead to transaction failures, which can discourage both merchants and consumers. Additionally, the need for continuous digital literacy education remains paramount. As digital payments evolve, so do the tactics of cyber-fraudsters, necessitating a permanent focus on consumer protection and cyber-security awareness.
Moving forward, the collaboration between Bank Indonesia and private entities like ShopeePay is expected to focus on deepening the functionality of QRIS. This includes the implementation of more advanced features such as cross-border payments, which would allow Indonesian MSMEs to accept payments from tourists and international customers seamlessly. The goal is to make the Indonesian payment ecosystem not just locally relevant, but globally competitive.
Conclusion: A New Standard for Indonesian Commerce
The event in Jakarta underscored a pivotal moment in the nation’s economic history. The transition to a cashless society, once considered a distant prospect, is now a reality for millions of Indonesians. By leveraging the vast user base of the Shopee ecosystem, ShopeePay has effectively catalyzed the adoption of QRIS among the most vital segment of the economy: the MSMEs.
As Bank Indonesia continues to refine its policies and platforms like ShopeePay continue to innovate their user experiences, the foundation for a more inclusive, efficient, and transparent financial system is being laid. The success of this endeavor will be measured not only by the number of QR codes displayed in storefronts but by the sustained growth and resilience of the small businesses that form the backbone of the Indonesian economy. The commitment displayed by all stakeholders at the September 16 event suggests that the momentum behind this digital transformation will only continue to accelerate in the coming years.