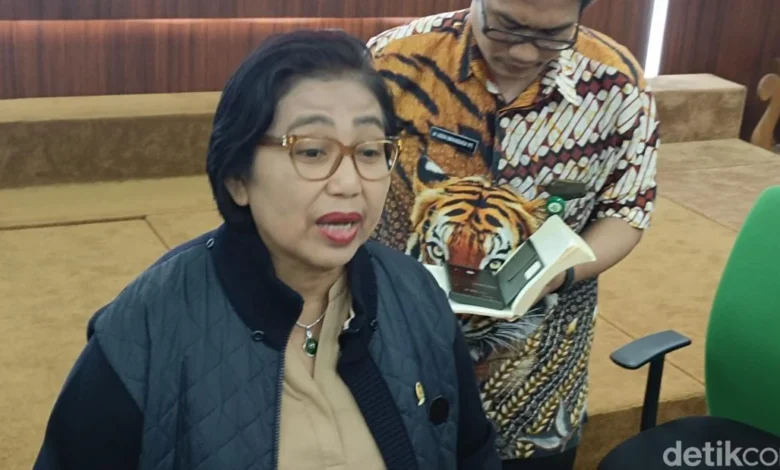
Jakarta – The debate surrounding the imposition of Value Added Tax (VAT) on feminine hygiene products in Indonesia has escalated significantly following a firm stance taken by a high-ranking legislator. Irma Suryani Chaniago, a member of Commission IX of the House of Representatives (DPR RI) representing the NasDem Party, has openly criticized the policy, demanding that the government completely eliminate the 11% VAT applied to sanitary pads. According to Chaniago, menstruation is a biological certainty and sanitary napkins constitute an indispensable fundamental necessity for women, rendering taxation on such items inherently unjust.
The controversy has captured national attention, bridging discussions on fiscal policy, human rights, gender sensitivity, and economic equity. As the government attempts to optimize state revenues to fund national development programs, policymakers find themselves at a crossroads, balancing fiscal targets against the socio-economic burdens placed on vulnerable populations. The ongoing discourse highlights a profound tension between state revenue collection strategies and the affordability of basic human necessities, particularly for women and girls across various socio-economic strata.
Legislative Push Against Gender-Insensitive Taxation
Speaking to reporters in Jakarta, Irma Suryani Chaniago expressed strong disapproval of taxing a commodity that is critical for women’s health, hygiene, and daily functioning. She argued that because sanitary pads are part of a routine, monthly expenditure that cannot be avoided or substituted, applying a consumer tax penalizes women simply for their biological makeup.
"Pads are a part of women’s routine monthly expenditure," Chaniago stated. She emphasized that fiscal policies must inherently integrate gender-sensitive frameworks. In her view, the Ministry of Finance should not pursue state revenue streams at the expense of ordinary citizens, especially when the tax burden falls disproportionately on essential health commodities.
Chaniago further elaborated that the state should target more appropriate, non-essential commodities for revenue maximization rather than taxing basic hygiene goods. She pointed out that consumers already bear various layers of taxation during the purchasing process, making the additional VAT burden on sanitary items an unnecessary hardship. As a senior member of the House and a central board chairperson of the NasDem Party, Chaniago warned that the continuation of this policy holds high potential for overburdening vulnerable and low-income groups, for whom the cumulative cost of basic hygiene products represents a tangible portion of their monthly household budgets.
Chronology of the Controversy and Legal Challenges
The current political debate did not emerge in a vacuum; it is the culmination of mounting public dissatisfaction and formal legal maneuvers challenging Indonesia’s tax architecture. The timeline of this issue traces back through recent legislative developments and judicial activism:
- October 29, 2026: The Directorate General of Taxes (DJP) officially clarifies the status of sanitary pads under Indonesian tax law, confirming that they are classified as Taxable Goods (Barang Kena Pajak – BKP) and are subject to the prevailing VAT regulations.
- November 2, 2026: A citizen named Bernita Matondang formally files a judicial review petition at the Constitutional Court (Mahkamah Konstitusi) targeting Law Number 7 of 2021 concerning the Harmonization of Tax Regulations (UU HPP). Registered under case number 406/PUU-XXIV/2026, the petitioner explicitly asks the court to mandate that menstrual pads be categorized as tax-exempt goods.
- November 4, 2026: Member of Commission IX DPR RI, Irma Suryani Chaniago, publicly responds to the escalating controversy, strongly urging the government to scrap the 11% VAT on sanitary pads, citing their status as fundamental non-discretionary goods for women.
The legal challenge initiated by Bernita Matondang serves as the primary catalyst for the renewed legislative and public scrutiny. By targeting Article 16B paragraph (1a) letter j number 1 and the explanation thereof within the Harmonization of Tax Regulations Law, the petitioner seeks to compel the judiciary to address what many advocacy groups describe as a structural oversight in the nation’s tax exemptions.
Official Stance of the Directorate General of Taxes
In response to public inquiries and emerging legal challenges, the Directorate General of Taxes (DJP) provided a detailed breakdown of how sanitary pads are treated under current fiscal statutes. Inge Diana Rismawanti, Director of Counseling, Services, and Public Relations at the DJP, explained that sanitary pads currently fall squarely within the category of general commercial commodities subject to standard taxation frameworks.
"On principle, sanitary pads traded in Indonesia are Taxable Goods subject to Value Added Tax, provided that their delivery fulfills the prevailing tax provisions," Rismawanti stated.
She further clarified the mechanics of the tax rate calculation. For non-luxury goods, the statutory VAT rate is set at 12%, accompanied by a tax base calculation mechanism utilizing a specific alternative value equivalent to 11/12 of the actual selling price. Consequently, the effective VAT burden shouldered by the final consumer remains steady at approximately 11%.
Rismawanti acknowledged that while certain strategic goods—such as specific basic foodstuffs, medical services, and educational tools—receive tax exemptions or facilities under the law, sanitary products have not yet been incorporated into the specific group of commodities granted full tax liberation or facility status. This regulatory reality underscores why legislative amendments or judicial interventions are required if the tax status of these items is to change.
Economic Implications and the Global "Tampon Tax" Movement
The debate in Indonesia mirrors a broader global movement challenging the taxation of menstrual products, frequently referred to in international advocacy as the "tampon tax." For decades, activists, feminist organizations, and public health advocates around the world have argued that applying luxury or standard consumer tax rates to essential sanitary items constitutes a form of gender-based economic discrimination.
From an economic perspective, taxing inelastic goods—products for which consumer demand remains relatively constant regardless of price changes—places a regressive burden on lower-income households. Because menstruation is an unavoidable biological process, individuals cannot simply opt out of purchasing sanitary products when prices rise due to taxation or inflation. For impoverished and vulnerable communities, the cost of menstrual hygiene management can force difficult trade-offs between purchasing food, paying for utilities, or buying necessary health supplies.
Public health specialists emphasize that adequate menstrual hygiene management is inextricably linked to broader developmental outcomes, including educational retention for young girls and workplace participation for adult women. When sanitary products become financially burdensome, instances of absenteeism in schools and workplaces rise, leading to long-term socio-economic setbacks. Consequently, removing the VAT on sanitary pads is viewed by economists not merely as a minor tax adjustment, but as an investment in human capital, gender equality, and public health equity.
Broader Public Reaction and Future Outlook
The convergence of the constitutional lawsuit filed by Bernita Matondang and the high-profile legislative push by lawmakers like Irma Suryani Chaniago has turned the tax status of sanitary pads into a litmus test for the government’s responsiveness to gender equity issues. Civil society organizations, consumer rights groups, and online advocacy networks have amplified the discourse, demanding that the Ministry of Finance review its exemption classifications.
As the Constitutional Court begins deliberations on case number 406/PUU-XXIV/2026, and as pressure mounts within the House of Representatives, the executive branch faces a strategic decision. The Ministry of Finance must weigh the modest fiscal contribution generated by the VAT on sanitary products against the significant political, social, and moral costs of maintaining a tax that critics label as inherently discriminatory against women.
Ultimately, the ongoing controversy highlights the complex interplay between macroeconomic policy and social justice in modern Indonesia. Whether through a landmark judicial ruling by the Constitutional Court or a proactive policy revision by the government to amend tax exemption schedules, the outcome of this debate will set a crucial precedent for how foundational health and hygiene needs are addressed within the nation’s legal and fiscal frameworks.